Short answer
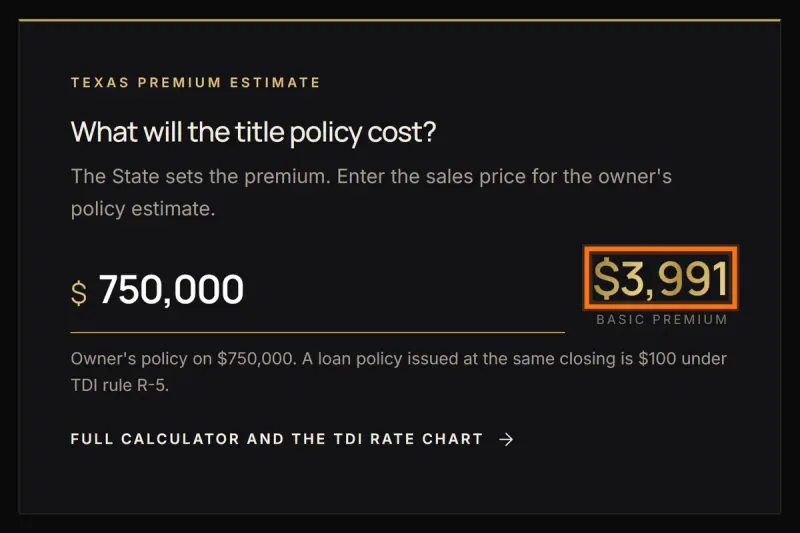
On a $750,000 home in Dallas, the owner's title policy premium is $3,991 under the Texas rates in effect since March 1, 2026, and it is the same at every title company because the Texas Department of Insurance sets it. A lender's policy issued at the same closing adds $100, plus any endorsements the lender requires. Who pays is decided in the contract: Paragraph 6.A of the TREC resale contract has a checkbox for the seller or the buyer to pay for the owner's policy, and the buyer pays for the loan policy.
This guide answers
- How much does title insurance cost on a $750,000 home in Dallas?
- Who pays for title insurance when buying a home in Dallas, Texas, the buyer or the seller?
Key takeaways
- The 2026 Texas owner's policy premium on a $750,000 home is $3,991, paid once at closing, at every title company in Dallas.
- A loan policy issued at the same closing is $100 under Rate Rule R-5, as long as the loan is not larger than the price.
- Paragraph 6.A of TREC contract 20-19 lets the parties check whether the seller or the buyer pays for the owner's policy. It is negotiated, not fixed by law.
- The buyer pays for the loan policy and the lender's endorsements under Paragraph 12.A(2), unless the seller agrees to a contribution.
- The escrow fee, tax certificates, recording and delivery charges are not part of the premium. Each company sets its own, so ask for them in writing.
A $750,000 Dallas home carries a $3,991 owner's title premium
The owner's title policy on a $750,000 home in Dallas costs $3,991 under the Texas premium rates in effect since March 1, 2026. If you finance the purchase, the lender's policy issued at the same closing adds $100, plus any endorsements your lender requires. The premium is paid once, at closing, and never again for as long as you own the home.
That figure does not depend on which title company you use. Texas title insurance premiums are promulgated, meaning the Texas Department of Insurance (TDI) sets them under Texas Insurance Code Section 2703.151, and every company must charge the same premium for the same policy. A $750,000 home in Lakewood, Preston Hollow, Plano or Frisco carries the same $3,991.
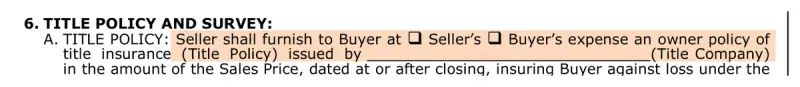
Who pays it is a separate question, and the answer is in your contract. On a resale, Paragraph 6.A of the Texas Real Estate Commission (TREC) contract has two checkboxes: the owner's policy is furnished at the seller's expense or at the buyer's expense. The buyer pays for the lender's policy. Both points are covered below, with the contract wording.
This guide is the price list. It gives the premium for common Dallas home prices, shows what is added on a financed purchase, and separates the state-set premium from the fees each company sets itself. For why Texas prices title insurance this way, see are title insurance rates the same at every Texas title company.
Title premiums for common Dallas home prices
The premium follows the policy amount, and on a home purchase the owner's policy is written in the amount of the sales price. The table works the current TDI chart for prices from $300,000 to $2,000,000.
Texas owner's title policy premium by home price (rates effective March 1, 2026)
| Sales price | Owner's policy premium | With a $100 loan policy at the same closing | Survey amendment, if chosen (5 percent) |
|---|---|---|---|
| $300,000 | $1,768 | $1,868 | $88.40 |
| $400,000 | $2,262 | $2,362 | $113.10 |
| $500,000 | $2,756 | $2,856 | $137.80 |
| $600,000 | $3,250 | $3,350 | $162.50 |
| $750,000 | $3,991 | $4,091 | $199.55 |
| $900,000 | $4,732 | $4,832 | $236.60 |
| $1,000,000 | $5,226 | $5,326 | $261.30 |
| $1,250,000 | $6,241 | $6,341 | $312.05 |
| $1,500,000 | $7,256 | $7,356 | $362.80 |
| $2,000,000 | $9,286 | $9,386 | $464.30 |
How to read this table: find your price in the first column. The second column is the owner's policy by itself, which is all a cash buyer needs. The third column adds the $100 lender's policy for a financed purchase where the loan is no larger than the price. The last column is the extra premium if the contract calls for the survey exception to be amended, explained further down. Lender endorsements and the company-set fees are not in this table.
Two things stand out. The premium is a little over half of one percent of the price across the whole range: $3,991 is about 0.53 percent of $750,000. And it rises more slowly above $1 million, because the rate per $1,000 drops from $4.94 to $4.06 at that point.
If your price falls between rows, our Texas title premium calculator gives the figure for any amount above $100,000.
How the $3,991 is calculated
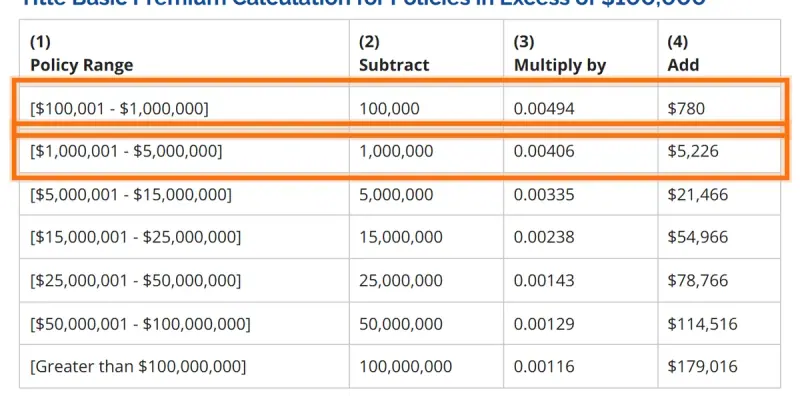
You can check the number yourself in under a minute. TDI publishes the basic premium rates effective March 1, 2026 with a four-step method for any policy above $100,000:
- Find the range. $750,000 falls in the range from $100,001 to $1,000,000.
- Subtract. $750,000 minus $100,000 leaves $650,000.
- Multiply and round to the nearest dollar. $650,000 times 0.00494 is $3,211.
- Add. $3,211 plus $780 is $3,991.
Above $1 million the same steps use the next row. For a $1,500,000 home: subtract $1,000,000, multiply the remaining $500,000 by 0.00406 to get $2,030, and add $5,226 for a premium of $7,256.
Three details keep the figure accurate:
- The chart changes by order of the Commissioner of Insurance. A premium copied from a closing statement dated before March 1, 2026, or from an old online calculator, will not match today's chart.
- The price that counts is the final contract price. If an amendment moves the price from $750,000 to $735,000, the premium moves with it, to $3,917.
- The county does not matter. Dallas, Collin, Denton and Tarrant County homes are all priced from the same statewide chart.
The lender's policy and the endorsements added to it
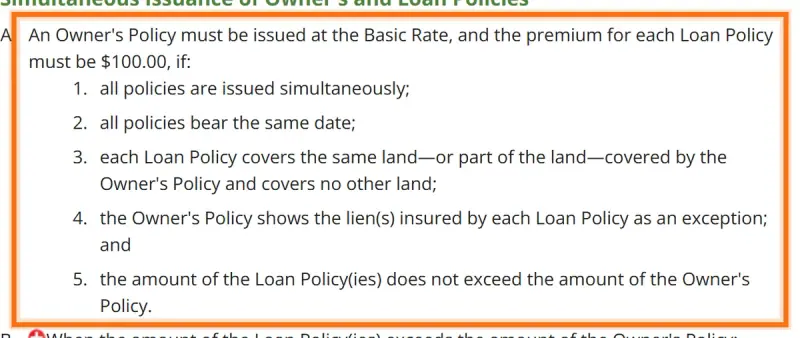
A mortgage lender will require its own title policy, the loan policy, which insures the lender's lien and not your ownership. Under TDI Rate Rule R-5, when the owner's policy and the loan policy are issued together, bear the same date, cover the same land, the owner's policy lists the lender's lien as an exception and the loan is not larger than the owner's policy amount, the loan policy premium is $100.
Lenders also ask for endorsements, which are short additions to the loan policy. Each has a premium set by TDI. The ones a Dallas home buyer sees most often:
- T-19, restrictions, encroachments and minerals. On residential property, 5 percent of the basic rate with a $50 minimum (Rate Rule R-29).
- T-17, planned unit development. $25, for a home in a planned unit development (Rule R-11).
- T-36, environmental protection lien. $25 (Rule R-11).
- T-33, variable rate mortgage. $20, only on an adjustable-rate loan (Rule R-11).
- Tax wording. Adding "not yet due and payable" to the tax exception is $5 under Rule R-24.
- Survey amendment on the loan policy. $0 under Rule R-16.
Title premiums on a $750,000 Dallas purchase with a $600,000 loan
| Item | TDI rule | Premium | Who pays under TREC 20-19 |
|---|---|---|---|
| Owner's policy, $750,000 | Basic rate | $3,991.00 | Seller or buyer, as checked in 6.A |
| Loan policy, $600,000, same closing | R-5 | $100.00 | Buyer |
| Survey amendment on the owner's policy | R-16, 5 percent | $199.55 | Buyer or seller, as checked in 6.A(8) |
| T-19 endorsement on the loan policy | R-29, 5 percent of the $3,250 basic rate on $600,000 | $162.50 | Buyer |
| T-17 endorsement, if the home is in a planned unit development | R-11 | $25.00 | Buyer |
| T-36 endorsement | R-11 | $25.00 | Buyer |
| Total if all six apply | $4,503.05 |
What this means for you: the owner's policy is almost nine-tenths of the title premium on a financed $750,000 purchase. Everything a lender adds comes to a few hundred dollars. Your lender's closing instructions decide which endorsements apply, so treat the last three rows as typical, not certain.
The table also answers a question buyers ask when closing costs feel high: what if I skip the owner's policy? The $100 price exists only when the two policies are issued together. A loan policy issued alone is charged the basic rate on the loan amount, which is $3,250 on $600,000. Declining the owner's policy would save about $841 of the $4,091, and leave your own $750,000 purchase uninsured. Our guide to the owner's policy and the lender's policy in Texas explains what each one covers.
Who pays: the buyer or the seller?
Texas law does not assign the cost to either side. TDI's consumer guidance says the buyer and seller may negotiate who pays the premium, and the contract records what they agreed.
Most Dallas resale homes are sold on the TREC One to Four Family Residential Contract (Resale), currently form 20-19, effective July 1, 2026. It splits the title costs this way:
- Owner's policy: negotiable. Paragraph 6.A reads: "Seller shall furnish to Buyer at Seller's or Buyer's expense an owner policy of title insurance," with a box to check beside each party, "in the amount of the Sales Price." The seller always furnishes it. The checkbox decides who pays for it.
- Loan policy and lender endorsements: buyer. Paragraph 12.A(2) lists the "loan title policy with endorsements required by lender" among the buyer's expenses.
- Survey amendment: negotiable. Paragraph 6.A(8) lets the parties leave the standard boundary exception alone or have it amended to read "shortages in area" at the expense of the buyer or the seller, again by checkbox.
- Escrow fee: split. Paragraphs 12.A(1) and 12.A(2) put one-half of the escrow fee on each side.
- Seller credit. Paragraph 12.A(1)(b) has a blank for an amount the seller agrees to pay toward the buyer's expenses, which can absorb the buyer's title charges.
In North Texas, sellers often agree to pay for the owner's policy on a resale, but that is custom and negotiating position, not a rule. When several buyers are competing for a house, a buyer may offer to pay it. When a house has been on the market for a while, the seller usually does.
What the checkbox is worth on a $750,000 sale
For the seller, a checked "Seller's" box is a $3,991 line on the seller's side of the closing statement, and $4,190.55 if the seller also takes the survey amendment. For the buyer, the same boxes checked the other way add those amounts to the cash needed at closing. Either way it is real money, so decide it when the offer is written, not at the closing table.
The same paragraph names the title company. Our guide to who chooses the title company in a Texas deal covers how that choice is made and the limits on steering it.
What is not the premium: escrow fee, recording and other charges
The premium is one group of lines on the closing statement. Other title-related charges sit beside it, and unlike the premium they are not set by the state. TDI's title insurance FAQ names tax certificates, escrow fees, recording fees and delivery expenses as extra charges most title companies add, and tells consumers they can shop for them.
- Escrow fee. The company's charge for running the closing: holding funds, preparing the settlement statement, paying off liens and disbursing. Each company sets its own. The TREC contract splits it between buyer and seller.
- Tax certificates. Ordered to confirm what is owed to each taxing authority. A seller's expense under Paragraph 12.A(1)(a).
- Recording fees. Charged by the county clerk to record the deed, the deed of trust and any releases. On a Dallas home that is the Dallas County Clerk.
- Copies of easements and restrictions. The documents behind the exceptions in your commitment, a buyer's expense under the contract.
- Courier, delivery and wire fees. Small, and listed among the buyer's expenses.
- The survey. Paid to a surveyor, not the title company, by whichever side Paragraph 6.C names.
We do not print dollar figures for these here, because they depend on the transaction and the right number is the one written for your deal. Ask any title company you are considering for its fee sheet for your price, loan amount and county, and compare the total of these lines. The premium columns will match to the dollar. These will not.
One comparison to avoid: an offer to discount or rebate the premium itself. TDI's FAQ answers the question of whether you can get a discount with one word, no.
Why your Loan Estimate shows different title numbers
Many Dallas buyers work out $3,991 and $100, then open the lender's Loan Estimate and find an owner's title premium that is much lower and a lender's title premium that is much higher. Nothing is wrong, and you are not being charged twice.
Federal disclosure rules and Texas rules show the same two policies differently. Texas puts the simultaneous-issue saving on the loan policy, which is why it is $100. The federal forms show that saving on the owner's policy instead. TDI's Texas Disclosure, Form T-64, says so in plain words and adds the check that matters: add the two premiums on the Closing Disclosure and the total should equal the total of the two premiums on the Texas form.
Under TDI Procedural Rule P-73, whenever a federal Closing Disclosure is used in a Texas closing, the settlement agent must also prepare the T-64. It states the Texas title premiums accurately and itemizes the other fees paid to the settlement agent. For a $750,000 purchase with a loan, the two premiums should total $4,091 on both documents before endorsements.
This matters most when buyer and seller are splitting title costs. The seller who agreed to pay for the owner's policy owes the Texas figure, $3,991, not the smaller number printed on the buyer's federal form. The T-64 is the document that settles it. Our walk-through of how a Dallas home closing works shows where these documents arrive in the timeline.
New construction and cash purchases
Buying a new home from a builder
The premium comes from the same chart, applied to the price of the home. A $750,000 new build in a Dallas-area subdivision carries the same $3,991 owner's premium as a $750,000 resale.
What changes is the contract. The TREC resale form is not for new homes sold by a builder. TREC publishes separate New Home Contracts for completed and incomplete construction, and many builders use their own contract instead. Whichever you sign, find the title policy paragraph before you sign and confirm three things: who pays for the owner's policy, which title company is named, and who pays for the survey and the survey amendment. If the builder's contract says the builder pays some closing costs, ask in writing which title charges that covers.
Paying cash
With no lender there is no loan policy, no $100 line and no lender endorsements. The owner's policy is the whole title premium: $3,991 on $750,000. It is also optional in the sense that nobody requires it, which makes it the one decision a cash buyer has to make alone. The checkbox in Paragraph 6.A works the same way with or without a loan, so a seller who agreed to pay still pays.
Our guide to buying a Dallas home with cash covers what the policy protects when there is no lender checking the title for you.
How to get the exact figure before you sign
You can know your title premium to the dollar before the offer goes out. The steps:
- Run the price. Enter the offer price in the premium calculator. That is the owner's policy.
- Add $100 if you are financing and the loan is no larger than the price.
- Decide on the survey amendment. If box (ii) in Paragraph 6.A(8) will be checked, add 5 percent of the owner's premium (minimum $20), and confirm there is a survey the title company can accept.
- Ask your loan officer which endorsements the lender requires. Price them from the list above.
- Check the boxes on purpose. Paragraph 6.A for the owner's policy, 6.A(8) for the survey amendment, 6.C for the survey, and 12.A(1)(b) if the seller is contributing to your costs.
- Ask the title company for its fees in writing. Escrow fee, tax certificates, recording estimate and delivery, for your price, loan amount and county.
Sellers can run the same steps in reverse to build a net sheet: the owner's premium if the seller's box is checked, half the escrow fee, tax certificates and the cost of releasing the existing mortgage.
The figures become final when the title commitment and the closing statement are issued. If the price or the loan amount changes during the option period, the premiums change by the same formula. The commitment is also where an unpaid lien, a missing heir or a boundary conflict shows up. Clearing those does not change the premium, but it can change the closing date, and our problem title and curative work page explains how they are resolved.
Because the premium is identical everywhere, what you are choosing in a title company is the work behind it. Aurum Title Inc. is a Texas title agent (TDI license 2752531) at 8150 N Central Expy, Suite 1100, in Dallas. We are attorney-owned, our executive escrow officer, Austin Pennington, is an attorney, and our licensed escrow officers are Austin Pennington, Monday Locklear and Kay Alton Farr, working on a systemized process. Policies are underwritten by Chicago Title, Fidelity National Title and Westcor. Our residential title and escrow page describes how we handle home closings.
If you have a Dallas home under contract or an offer about to go out, you can open a title order with the contract attached, or call (214) 306-8606 and ask for a fee quote. An escrow officer will confirm the premiums and our fees for that transaction.
Frequently asked questions
How much does title insurance cost on a $750,000 home in Dallas?
The owner's policy premium is $3,991 under the Texas Department of Insurance rate chart effective March 1, 2026. With a mortgage, the lender's policy issued at the same closing adds $100, and lender endorsements usually add a few hundred dollars more. Every title company in Texas charges these same premiums.
Who pays for title insurance when buying a home in Dallas, Texas, the buyer or the seller?
It is negotiated. Paragraph 6.A of the TREC resale contract has a checkbox for the seller or the buyer to pay for the owner's policy, and sellers often agree to pay it in North Texas. The buyer pays for the lender's policy and its endorsements under Paragraph 12.A(2), unless the seller gives a credit toward the buyer's expenses.
Is title insurance on a Dallas home paid every year?
No. It is a one-time premium paid at closing. The owner's policy has no renewal and no annual bill, unlike homeowners insurance.
Can I get a lower title premium by shopping around in Dallas?
Not on the premium. The state sets it, so a $750,000 owner's policy is $3,991 at any Texas title company and no company may discount it. You can compare the escrow fee and the other charges each company sets for itself.
How much is the lender's title policy on a $600,000 mortgage?
It is $100 when it is issued at the same closing as an owner's policy and the loan does not exceed the price. If no owner's policy is issued, the loan policy is charged the full basic rate, which is $3,250 on $600,000.
Why does my Closing Disclosure show a smaller owner's title premium than $3,991?
The federal form shows the simultaneous-issue saving on the owner's policy, while Texas shows it on the loan policy. The two premiums added together should match on both documents. The Texas Disclosure, Form T-64, shows the actual Texas premium for each policy.
Does title insurance cost more on a new construction home in Dallas?
No. The premium comes from the same state chart applied to the price, so a $750,000 new home and a $750,000 resale carry the same owner's premium. What differs is the contract: a builder's contract or a TREC New Home Contract decides who pays, so read its title policy paragraph.
What does the survey amendment cost on a $750,000 home?
On residential property it is 5 percent of the owner's policy premium, which is $199.55 on a $3,991 premium. The contract's Paragraph 6.A(8) says whether the exception is amended and whether the buyer or the seller pays for it. On the loan policy the amendment is $0.
Related services
Residential